

|
|
|
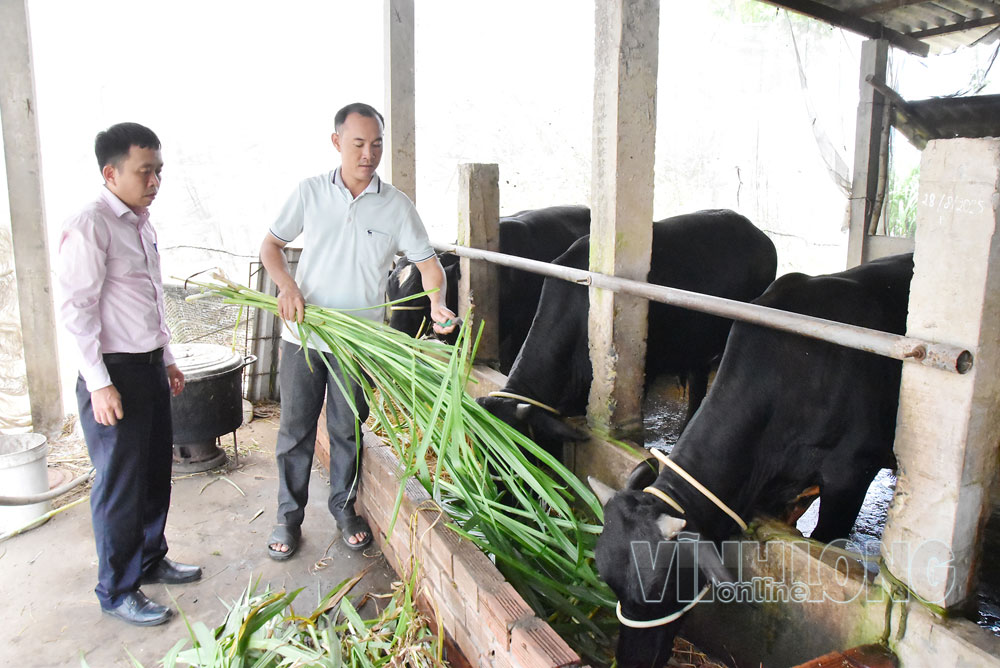
Thanks to policy-based credit, Mr. Hua Minh Xuyen's family (on the right) has effectively developed a cattle fattening model, becoming a well-off household. |



VISITORS


News & Events
Updated: 2026-08-10 09:26:01
Policy credit funds help the Khmer people develop their economy
(VBSP News) Through the coordination of local authorities, entrusted socio-political organizations, savings and loan groups, and village people's committees, policy credit funds are disbursed promptly and to the right beneficiaries. With these preferential funds, many poor and near-poor households and Khmer people have had the opportunity to develop production, expand their businesses, create jobs, and gradually rise out of poverty.
According to Mr. Tang Quoc Tinh, Deputy Director of the Tra Cu Branch of the Vietnam Bank for Social Policies (VBSP), the unit always closely coordinates with local authorities, entrusted political and social organizations, the VBSP Center, and the hamlet's people's committee in propaganda, evaluation, inspection, and supervision. As a result, capital is disbursed promptly and to the right recipients, helping many households invest in production, create jobs, and increase income.
In the first six months of the year, total capital reached over 1 trillion VND, an increase of nearly 46 billion VND compared to the beginning of the year. Of this, capital from the central government accounted for over 76% of the total; local budget capital reached over 175 billion VND; and capital mobilized from deposits of organizations and individuals, along with savings deposits through the Savings and Credit Center, reached over 68 billion VND.
In the first six months of the year, the unit lent nearly 170 billion VND to over 4,200 households, with debt collection reaching over 131 billion VND. The total outstanding debt of the socio-economic development programs reached nearly 975 billion VND, an increase of over 38 billion VND compared to the beginning of the year, with 22,600 poor households, near-poor households, and policy beneficiaries still having outstanding debt, contributing to meeting the capital needs for production and business investment, creating livelihoods and increasing income for people in the area.
Along with credit growth, the operational quality of the Savings and Credit Center network has improved. Currently, there are 515 groups in the area, of which nearly 68% are rated good, nearly 25% are rated fair, and there are no weak groups. By the end of June 2026, 97% of borrowing households will participate in savings deposits through the Savings and Credit Center.
In Ham Giang commune, after the merger with Thanh Xuyen hamlet, there are 779 households with 3,500 inhabitants, of which the Khmer people account for about 78%. The people mainly live by agricultural production with crops and livestock such as rice, sugarcane, and cattle farming; in recent years, many households have boldly converted inefficient sugarcane fields to farming giant freshwater prawns and whiteleg shrimp. However, many households still face difficulties in terms of capital, production techniques, and the application of science and technology.
Khmer farmer Hua Minh Xuyen (Thanh Xuyen hamlet), formerly a disadvantaged household, received a 30 million VND loan from the Social Policy Bank in 2019 to invest in buying two cows for fattening. After each breeding cycle, he uses a portion of the profit to renovate the barns, and the remaining capital is reinvested in buying breeding cows for further fattening. On average, each cow yields a profit of approximately 10 million VND after sale.
Seeing the model's effectiveness, he increased his loan to 40 million VND to expand his livestock farming and maintain a herd of 3 cows. Besides raising cattle, his family also cultivated 3 acres of sugarcane, utilized the field edges to grow grass for the cows, and took on odd jobs to cover farming expenses. As a result, the family's economy gradually stabilized, and they rose to become a well-off household.
The TDCS (Trade Development and Support Fund) supports agricultural development and creates opportunities for young people to develop service industries. Mr. Tram Ngoc Trang (born in 1994), residing in Thanh Xuyen hamlet, received a loan of 50 million VND to expand his business of makeup artistry and renting traditional Khmer costumes. With this capital, in addition to investing in more costumes, accessories, and equipment for his work, he and his mother sew and bead various belts, accessories, and decorative items to diversify their products and reduce input costs.
|
|
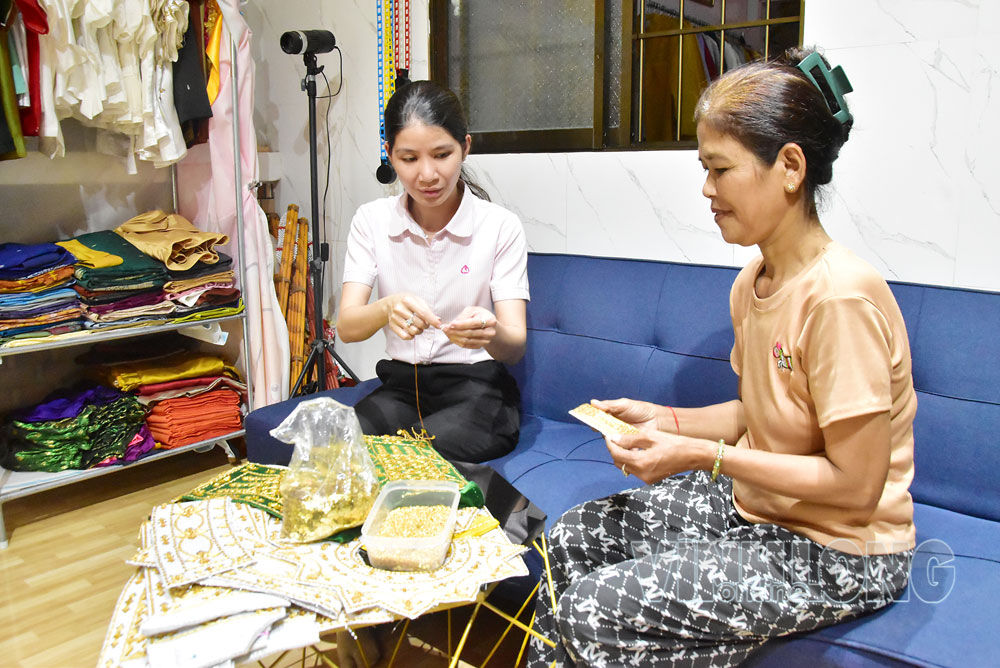
Ms. Kim Thi Chinh (on the right) is beading various types of belts for the traditional costumes of the Khmer people.
According to Trang's mother, Kim Thi Chinh, accessories that complement the traditional Khmer costume sell for between 300,000 and 10 million VND, depending on the type. Each costume is rented for between 300,000 and 700,000 VND. The preferential loan has helped him expand his business, better meeting the needs of people during festivals, weddings, and cultural events of the Khmer people, creating a stable income for his family.
The effective production and business models in Thanh Xuyen hamlet demonstrate the role of grassroots credit in helping households overcome capital difficulties, creating motivation for people to boldly transform production, invest in new industries, and effectively exploit the available potential of the locality.
“Besides the achievements, the Social Policy Bank's credit activities still face some difficulties such as high outstanding interest rates and some borrowers leaving the locality, making debt recovery and handling difficult. In the coming time, the Tra Cu Branch of the Social Policy Bank will continue to closely monitor credit growth targets, disburse funds promptly and to the right beneficiaries; strengthen the handling of overdue debts; consolidate the quality of operations of the Savings and Credit Centers; coordinate with localities and entrusted organizations to improve the effectiveness of social policy credit, contributing to achieving the goal of sustainable poverty reduction and ensuring social security in the area,” said Mr. Tang Quoc Tinh, Deputy Director of the Tra Cu Branch of the Social Policy Bank.
Text and photos: MY NHAN


LEARN MORE:
- Propose rising loan amounts for disadvantaged students
- Policy credit – a cornerstone for people's livelihoods
- Maximizing the effectiveness of preferential credit programs
- Preventing the relapse cycle
- When policy credit reaches the right place
- Policy credit provides impetus for the transformation of the Do Luong region
- Veterans engage in economic activities using policy-based credit funds
- Policy-based loans for students: A humanitarian pillar of support in the war-torn land of Quang Tri
- Lam Dong: Additional resources and more opportunities from policy-based credit
- Gia Lai: Policy-based credit provides support for students.
- Policy credit empowers vulnerable groups improve their livelihood
- Policy credit for the purpose of sustainable poverty reduction
- Providing policy credit to help women settle down and start up businesses.
- Enhancing the capacity to implement social policy finance
- VBSP Loans Help Former Offenders Rebuild Their Lives in Dak Lak
- 44,262 poor households, near-poor households, and other policy beneficiaries in Hanoi to access inclusive loans
- Policy credit give those who have gone astray a chance to turn their lives around
- More than four million students to access education loans from VBSP
- integrating digital technology into policy-based credit, farmers in Lang Son can pay interest from the comfort of their homes
- Partnership with NAPAS to boost digital financial services for the poor

- Policy credit – a cornerstone for people's livelihoods
- Maximizing the effectiveness of preferential credit programs
- Preventing the relapse cycle
- When policy credit reaches the right place
- Policy credit provides impetus for the transformation of the Do Luong region
- Veterans engage in economic activities using policy-based credit funds
- Policy-based loans for students: A humanitarian pillar of support in the war-torn land of Quang Tri
- Lam Dong: Additional resources and more opportunities from policy-based credit
- Gia Lai: Policy-based credit provides support for students.
- Savings & credit groups - A bridge between VBSP and borrowers


LENDING INTEREST RATE
|
||||||||||||||||||||
DEPOSIT INTEREST RATE
|
||||||||||